The Complete Mortgage Guide Nova for Northern Virginia
The Complete Mortgage Guide Nova for Northern Virginia
Mortgage financing in Northern Virginia requires pre-approval, credit review, and lender comparison across conventional, FHA, and VA loans. Homes365 by Eunice Johnson, based in Sterling, VA, guides buyers through rate locks, down payments, and closing costs with a dedicated 2-person team for personalized support.
Mortgage financing in Northern Virginia requires navigating loan programs, Virginia Housing down payment assistance, and pre-approval steps unique to Loudoun and Fairfax Counties. Homes365 by Eunice Johnson guides first-time buyers, move-up buyers, and investors through financing options across Ashburn, Herndon, and Reston, translating complex loan requirements into clear, actionable steps toward a confident closing.
Key Takeaways
- Northern Virginia median home prices require strategic financing planning for competitive offers.
- Fairfax County closings use settlement agents and deed of trust instruments, not traditional mortgages.
- Down payment requirements vary by loan type, affecting your total upfront investment and monthly payments.
- Local market knowledge determines success in Northern Virginia's competitive real estate environment and financing decisions.
Why Does Financing Feel Different in Northern Virginia?
Financing a home in Northern Virginia demands sharper preparation than in most of the state. Fairfax County purchase prices sit near a county median of roughly $813,000 as of mid-2026, and competing offers in that price range reward buyers who arrive with financing already in order. A well-prepared buyer wins the house; a slow one watches it slip away.
Real estate remains fundamentally a local business. Home costs vary widely depending on the region and metro area across Virginia, which means a mortgage guide nova residents can trust looks nothing like generic national advice. Loudoun and Fairfax Counties carry their own price tiers, inventory patterns, and buyer competition, all of which shape how to finance home northern virginia strategies from the first conversation with a lender onward.
Why Are Northern Virginia Mortgage Rates Important Right Now?
Rates set the monthly payment math that buyers live with for years. As of July 2025, the average 30-year fixed mortgage rate in Northern Virginia hovered near 6.9 percent, with shorter terms pricing somewhat lower. That figure directly narrows or expands what a buyer can comfortably offer on a home.
Three forces combine to make the region distinct:
- Elevated median prices concentrated in Fairfax County push buyers toward larger loan amounts.
- Multiple-offer scenarios favor buyers with documented, ready financing over those still shopping lenders.
- Rate sensitivity means small shifts in the 30-year fixed rate noticeably change affordability.
Homes365 by Eunice Johnson guides Northern Virginia clients through mortgage programs nova options suited to this landscape, pairing local market knowledge with disciplined pre-approval steps so financing readiness never becomes the reason an offer loses.
What Steps Make Up the Mortgage Process?
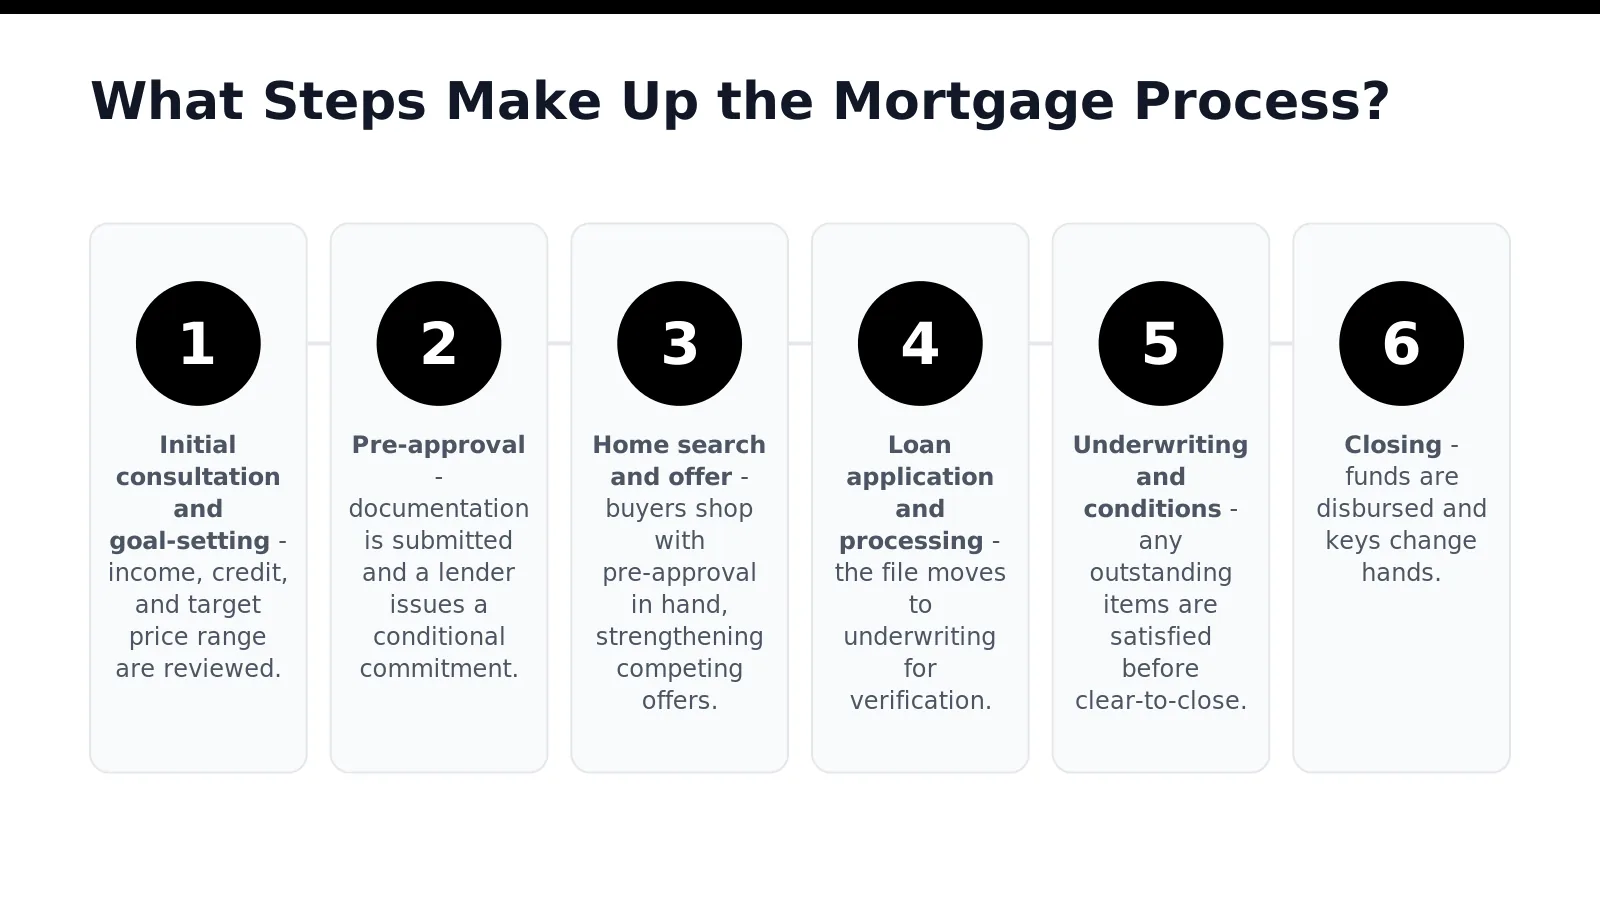
A sequence of defined stages carries a Northern Virginia buyer from first inquiry to settlement, each with its own timeline and its own set of requirements. Skipping a step, or misunderstanding what it demands, slows a file precisely when speed matters most in a competitive Loudoun or Fairfax County market. A sound mortgage guide nova buyers can trust lays out this sequence plainly: what each stage requires, roughly how long it takes, and which details most often cause delays locally.
The stages generally unfold as follows:
- Initial consultation and goal-setting - income, credit, and target price range are reviewed.
- Pre-approval - documentation is submitted and a lender issues a conditional commitment.
- Home search and offer - buyers shop with pre-approval in hand, strengthening competing offers.
- Loan application and processing - the file moves to underwriting for verification.
- Underwriting and conditions - any outstanding items are satisfied before clear-to-close.
- Closing - funds are disbursed and keys change hands.
Why does the order of these steps matter?
Each stage depends on the one before it. Attempting a home search before pre-approval, for instance, often means losing a desirable property to a buyer whose financing was already confirmed. Working through the sequence in order protects both timeline and negotiating position.
Who guides buyers through each stage in Northern Virginia?
Lenders serving Northern Virginia typically walk buyers through every step, so nothing arrives as a surprise between the first conversation and the final signature. Homes365 by Eunice Johnson complements that lender relationship directly. Its buying agent services coordinate each stage, from pre-approval through settlement, keeping the transaction moving smoothly for clients purchasing anywhere across Loudoun and Fairfax Counties. Understanding how to finance home northern virginia buyers pursue starts with this coordinated structure, not with isolated steps handled in silence.
How Do You Get Pre-Approved in NoVA?
Pre-approval in Northern Virginia begins with comparing lenders, not signing with the first one offered. Buyers who skip this comparison often accept weaker terms without realizing better rates existed down the street in Ashburn or Reston.
Why shop multiple lenders instead of choosing one?
Rates and terms shift from lender to lender, even within the same Loudoun or Fairfax County market. Shopping multiple local lenders across Northern Virginia, the District of Columbia, and Maryland remains the surest way to secure favorable pricing. Both fixed-rate and adjustable-rate mortgage products vary considerably by institution. A buyer evaluating only one offer has no benchmark for whether the terms are competitive. Comparing at least two or three local options before committing protects against overpaying across the life of the loan.
Before approaching any lender, readiness matters more than enthusiasm. Homes365 by Eunice Johnson offers free homebuyer education programs designed specifically to assess readiness. Prepare clients comprehensively for the purchase process ahead. These sessions walk buyers through financing fundamentals before a single application gets submitted, reducing the surprises that derail closings later.
What determines the down payment amount required?
Down payment size depends entirely on the loan program selected, not on a fixed industry standard. A buyer using one type of mortgage programs nova financing may owe far less upfront than another pursuing a conventional loan. This is why understanding how to finance home northern virginia purchases starts with matching the right program to the buyer's financial profile, not the other way around.
Three steps shape a sound pre-approval strategy:
- Gather income, asset, and credit documentation before contacting lenders
- Request quotes from multiple local institutions serving Northern Virginia
- Complete a homebuyer education program to clarify loan options and readiness
Following a structured mortgage guide nova approach like this one keeps buyers from entering a competitive offer situation underprepared. Clients ready to move forward can schedule a tour of available properties or request a virtual visit to explore listings remotely before finalizing financing decisions.
Which Mortgage Programs Suit Northern Virginia Buyers?
Loan selection depends on income, down payment capacity, and property goals across Loudoun and Fairfax Counties. Northern Virginia buyers draw from conventional, FHA, and VA loan programs, each carrying distinct qualification standards for credit, income, and occupancy. A sound mortgage guide NOVA buyers can trust starts with matching the right program to the right circumstance, rather than defaulting to whichever lender advertises loudest.
Down payment requirements vary widely among these mortgage programs NOVA lenders extend to local buyers. Options range from no-down-payment loans through low-down-payment paths, up to conventional mortgages requiring 10 to 20 percent down. Buyers without significant savings still have genuine paths to ownership. Limited cash reserves need not close the door on a Loudoun or Fairfax purchase.
How does financing actually work for a Northern Virginia purchase?
Financing a home in Northern Virginia means pairing one of these loan structures with available assistance resources before shopping actively. Virginia's Down Payment Assistance Program supports first-time homebuyers whose income falls at or below area median income limits, easing the upfront barrier that stalls many otherwise qualified households. Homes365 by Eunice Johnson, serving clients throughout Loudoun and Fairfax Counties from its Sterling, VA base, helps buyers align loan choice with assistance eligibility early in the search.
Which program fits a first-time buyer with limited savings?
Buyers facing a thin down payment generally fare best with no-down-payment or low-down-payment structures, layered with assistance program support where income qualifies. This combination preserves cash for closing costs and reserves. Those ready to schedule a tour of Northern Virginia properties gain the clearest sense of which program aligns with their target neighborhood and price range.
What Should First-Time Buyers Budget For?
Three categories demand attention before any offer reaches a seller in Loudoun or Fairfax County: the down payment, monthly insurance costs, and closing costs. Each shapes affordability differently, and overlooking one creates unwelcome surprises at the settlement table.
The down payment deserves the most deliberate planning. A larger sum placed upfront generally lowers the resulting monthly mortgage payment across the life of the loan, giving buyers more breathing room in their household budget. Clients weighing a smaller down payment against a larger one should understand this trade-off clearly before signing a purchase agreement.
Is mortgage insurance required for every buyer?
No. Mortgage insurance applies specifically to buyers who place less than 20 percent down on most loan types. These buyers should budget for monthly Private Mortgage Insurance premiums added to the standard principal and interest payment. This cost continues until sufficient equity accumulates, so factoring it into the monthly figure prevents an inaccurate affordability estimate.
What do Northern Virginia closing costs typically include?
Closing costs in Northern Virginia generally run between 3 and 5 percent of the purchase price. This range covers lender fees, title insurance, appraisal charges, state and county transfer taxes, and escrow setup.
- Down payment: influences monthly payment size and long-term interest paid
- Private Mortgage Insurance: required on most loans under 20 percent down
- Closing costs: 3 to 5 percent of purchase price, covering fees, title insurance, appraisal, and transfer taxes
Navigating these figures alongside a proper mortgage guide nova resource prevents budget shortfalls late in the process. Homes365 by Eunice Johnson translates Virginia Housing resources into actionable steps, guiding Northern Virginia buyers through financing options and down payment assistance programs with clarity and care. For those exploring how to finance home northern virginia purchases, a consultation that reviews mortgage programs nova wide, alongside personal budget realities, sets the foundation for a confident purchase. Buyers ready to move forward can Schedule a tour of available properties or Request a virtual visit to explore options from anywhere in Northern Virginia.
How Do Closing Costs Work in Virginia?
Closing costs in Northern Virginia settlements proceed through a settlement agent, with the purchase secured by a deed of trust rather than a traditional mortgage instrument, a distinction that shapes how fees and signatures are structured in Fairfax and Loudoun Counties. Buyers who overlook this step often arrive at the settlement table unprepared for the full scope of charges layered beyond the purchase price. Understanding this structure early protects both timeline and budget.
Expect closing costs across Northern Virginia to run between 3. 5 percent of the purchase price, according to Mortgage FAQ for Northern Virginia, Maryland, and Washington D.C. That range covers more than one line item. Lender fees, title insurance, and appraisal costs each contribute separately. State and county transfer taxes add a Virginia-specific layer most out-of-state buyers do not anticipate.
What Fees Should Loudoun and Fairfax Buyers Budget For?
Buyers financing property in Loudoun or Fairfax County should plan for several distinct charges beyond the loan amount itself:
- Lender origination and underwriting fees
- Title insurance and settlement agent charges
- Appraisal costs
- State and county transfer taxes
- Escrow setup for taxes and insurance
Does a Smaller Down Payment Raise Closing Costs?
A down payment below 20 percent does not expand standard closing costs. It does introduce Private Mortgage Insurance as an ongoing monthly expense. This premium continues until sufficient equity accumulates in the home. Buyers pursuing competitive mortgage programs nova lenders offer should weigh the lower upfront cash requirement against years of added monthly insurance payments.
Homes365 by Eunice Johnson guides clients through each fee line before settlement day arrives, so no figure feels unexpected. Buyers ready to see available properties in person can Schedule a tour. Those weighing options from a distance can Request a virtual visit to begin the financing conversation with clarity.
What Financing Options Exist for Investors?
Investors pursuing property across Loudoun and Fairfax Counties draw from a range of products beyond the standard thirty-year mortgage. A national bank headquartered in McLean, Virginia extends purchase, refinance, jumbo, construction, bridge, and portfolio financing to clients throughout the region. Portfolio and bridge structures matter here: they accommodate investors who need to close on a second Northern Virginia property before a prior sale settles, a common scenario in a market where inventory moves quickly.
Renovation and home equity products round out this lender's offerings, giving investors a path to fund improvements on acquired properties or draw equity from an existing Northern Virginia holding. This matters for anyone eyeing a dated Reston townhome or an Ashburn fixer-upper that needs capital beyond the initial purchase price.
Can investors use a D.C.-area lender for properties outside Virginia?
Lenders serving the greater Washington, D.C. region, Northern Virginia included, often lend nationwide, subject to applicable law and underwriting standards. This flexibility suits investors building a portfolio that spans beyond Loudoun and Fairfax Counties. Underwriting criteria still apply regardless of property location, so documentation and reserve requirements remain consistent across markets.
How many lenders should an investor compare?
Comparing several local lenders across Northern Virginia and the broader D.C. metro area before committing protects against overpaying on rate or terms. Fixed-rate and adjustable-rate options both deserve consideration, since investment strategy (short hold versus long hold) often dictates which structure performs better financially.
Homes365 by Eunice Johnson guides investors through this comparison process, connecting mortgage programs nova investors rely on with properties suited to their financing strategy. Clients weighing an investment purchase in Ashburn, Herndon, or Reston can schedule a tour of active listings. request a virtual visit when timelines or distance make an in-person walkthrough impractical.
How Does Homes365 Guide Your Financing Journey?
Homes365 by Eunice Johnson coordinates financing, down payment assistance, neighborhood selection, and closing for buyers across Loudoun and Fairfax Counties. Relocating clients and first-time purchasers alike receive guidance structured around a single goal: readiness at every stage. This is not a transactional handoff to outside parties. A continuous thread of support running from the first conversation to the final signature.
Based in Sterling, VA, Homes365 by Eunice Johnson serves buyers throughout Northern Virginia, bringing local financing knowledge to communities such as Ashburn, Herndon, and Reston. Proximity to these markets means familiarity with the loan programs, grant options, and timing nuances that shape offers in competitive Fairfax and Loudoun submarkets. A mortgage guide nova buyers can actually use starts with this kind of local grounding, not generic national advice.
What Does Homes365 Do Before a Buyer Talks to a Lender?
Free homebuyer education comes first. These sessions assess financial readiness and prepare clients comprehensively before any lender conversation begins, reducing surprises later in underwriting.
Who Manages the Steps Between Pre-Approval and Settlement?
The firm's buying agent services coordinate each stage directly, from pre-approval through final settlement. Clients are not left to piece together how to finance home northern virginia purchases on their own. Homes365 manages the sequence.
Coordination covers several essentials:
- Pre-approval preparation and lender introductions
- Evaluation of applicable mortgage programs nova buyers may qualify for
- Down payment assistance research
- Neighborhood selection aligned with budget
- Settlement coordination through closing
Operating as a small, two-person team keeps the process personal. Every client receives direct attention rather than being routed through a large, impersonal pipeline. Those ready to move forward can schedule a tour of available properties. Buyers still weighing options may prefer to request a virtual visit before committing to an in-person showing.
FAQ
Why is financing preparation so important in Northern Virginia?
Fairfax County median home prices sit near pricing varies and competing offers reward buyers who arrive with financing already arranged. A prepared buyer wins the house, while a slower one loses it.
How do Northern Virginia mortgage rates affect affordability?
As of July 2025, the average 30-year fixed rate in Northern Virginia hovered near 6.9 percent, directly narrowing or expanding what buyers can comfortably offer. Small rate shifts noticeably change affordability in this high-price market.
Who guides buyers through the Northern Virginia mortgage process?
Homes365 by Eunice Johnson, based in Sterling, VA, guides first-time buyers, move-up buyers, and investors through financing across Ashburn, Herndon, and Reston. The team translates complex loan requirements into clear steps toward closing.
Conclusion
In closing, navigating the intricacies of mortgage financing in Northern Virginia demands both discernment and expert guidance. The path toward homeownership, whether acquiring your inaugural residence, relocating for professional advancement, or expanding an investment portfolio, unfolds most gracefully when informed by comprehensive understanding and refined counsel. By engaging with the fundamental principles. Strategic considerations outlined throughout this guide, you position yourself to make decisions of enduring consequence, securing not merely a property. A legacy of financial prudence and residential excellence tailored to your distinctive circumstances and aspirations.